Related Content


  • Search

Capital Expenditure

It was reported in 2023 that many tertiary education institutions were reassessing the role of their campuses and realigning them with ambitious capital plans, often in partnership with private investors and/or government. While many of these institutions are poised to make significant capital investments, caution prevails.

As world events have unfolded, we have witnessed the enduring conflicts in the Ukraine and the Middle East, and we live with the uncertainty that has come with the Trump presidency. The global economy is shaped by slowing growth and falling inflation. The cost of construction remains high, although it appears to be stabilising now.

It is a complex environment at home too. In 2025, Australian institutions, alongside other large organisations, will begin mandatory climate-related financial reporting under the Corporations Act. In parallel, the Australian Federal Government has introduced caps on international students, with some institutions hit harder than others. Most institutions are grappling with the new patterns of working that have settled in following the Covid-19 pandemic and speculating about the future of teaching and learning. On a bright note, the New Zealand Government has just recently announced a new growth strategy that aims to double the economic impact of the higher education sector by 2034.

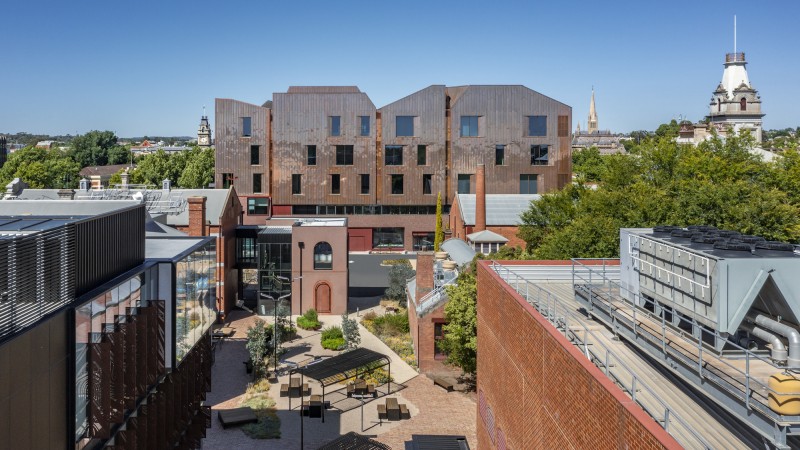
It is not surprising that decision makers remain cautious. Many ambitious plans for campus renewal projects, university cities and innovation quarters, appear to be moving slowly. Rather than implementing these plans at speed, there is a second agenda to strive for better utilisation of the existing estate – the goal is perhaps more about lifting the baseline than raising the bar, albeit in alignment with future ambitions.

Many institutions are leaning on utilisation data to determine the efficiency of their estates and carefully assess their space needs, with a view to consolidate to more efficient and affordable footprints, supported by more efficient and renewable energy infrastructures. Adaptive reuse and divestment of assets goes someway to addressing deferred liabilities.

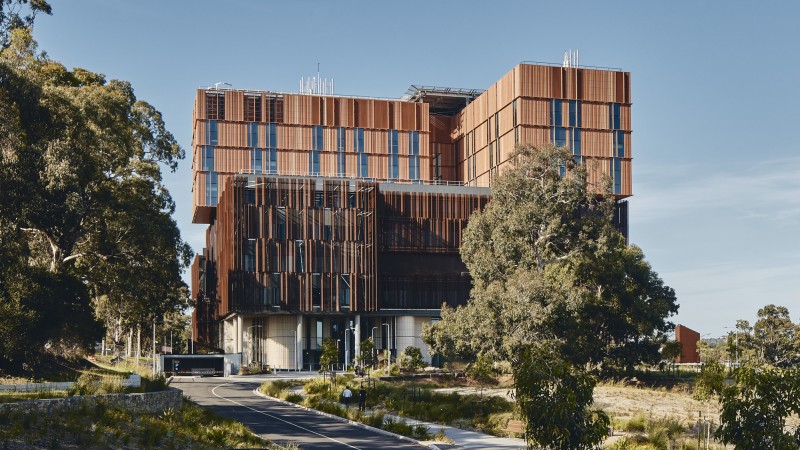
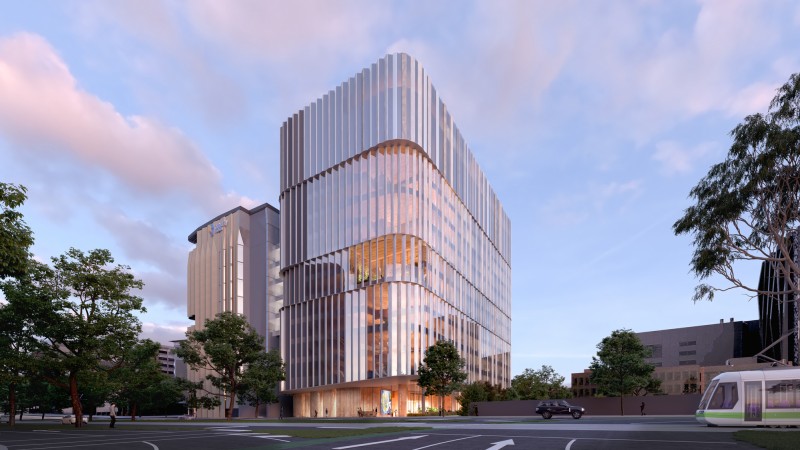
Investment in new buildings remains less compared with the pre-pandemic years. Fewer projects of lesser value are being delivered to address critical deficits in the estate and support interdisciplinary research. Specialist teaching and research spaces for life sciences and healthcare disciplines have been a focus, perhaps given the rapid development of technologies that support these disciplines.

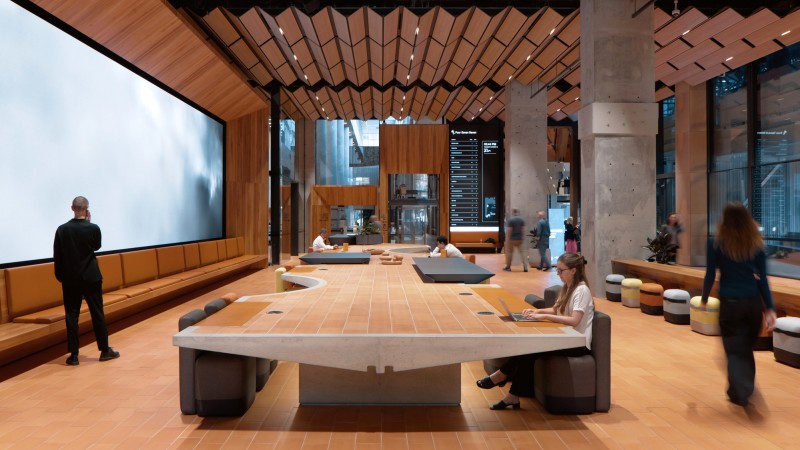
The student experience continues to be a key focus with some investment in central teaching and learning environments. Student surveys are being scrutinised to ascertain their needs and wants. Long commutes mean that the campus must be ‘better than home!’ to entice students there. Some institutions are making defensive moves to counter the uncertainty associated with the projected numbers of international students. This risk is sometimes being addressed with a real estate deal, taking advantage of a low market, and at other times with a new development.

This is all important work that will stand tertiary education institutions in good stead for better times ahead. When the sector recovers, we may see targeted investment aimed at improving international rankings, as Australian and Aotearoa/New Zealand institutions alike have slipped down a few places.

Thank you for registering

Subscribe

Lorem ipsum dolor sit amet, consectetuer adipiscing elit. Aenean commodo ligula eget dolor. Aenean massa. Cum sociis natoque penatibus et magnis dis parturient montes, nascetur ridiculus mus.

By choosing 'submit' you accept the terms of our privacy policy

Thank You

Your subscription has been successful